

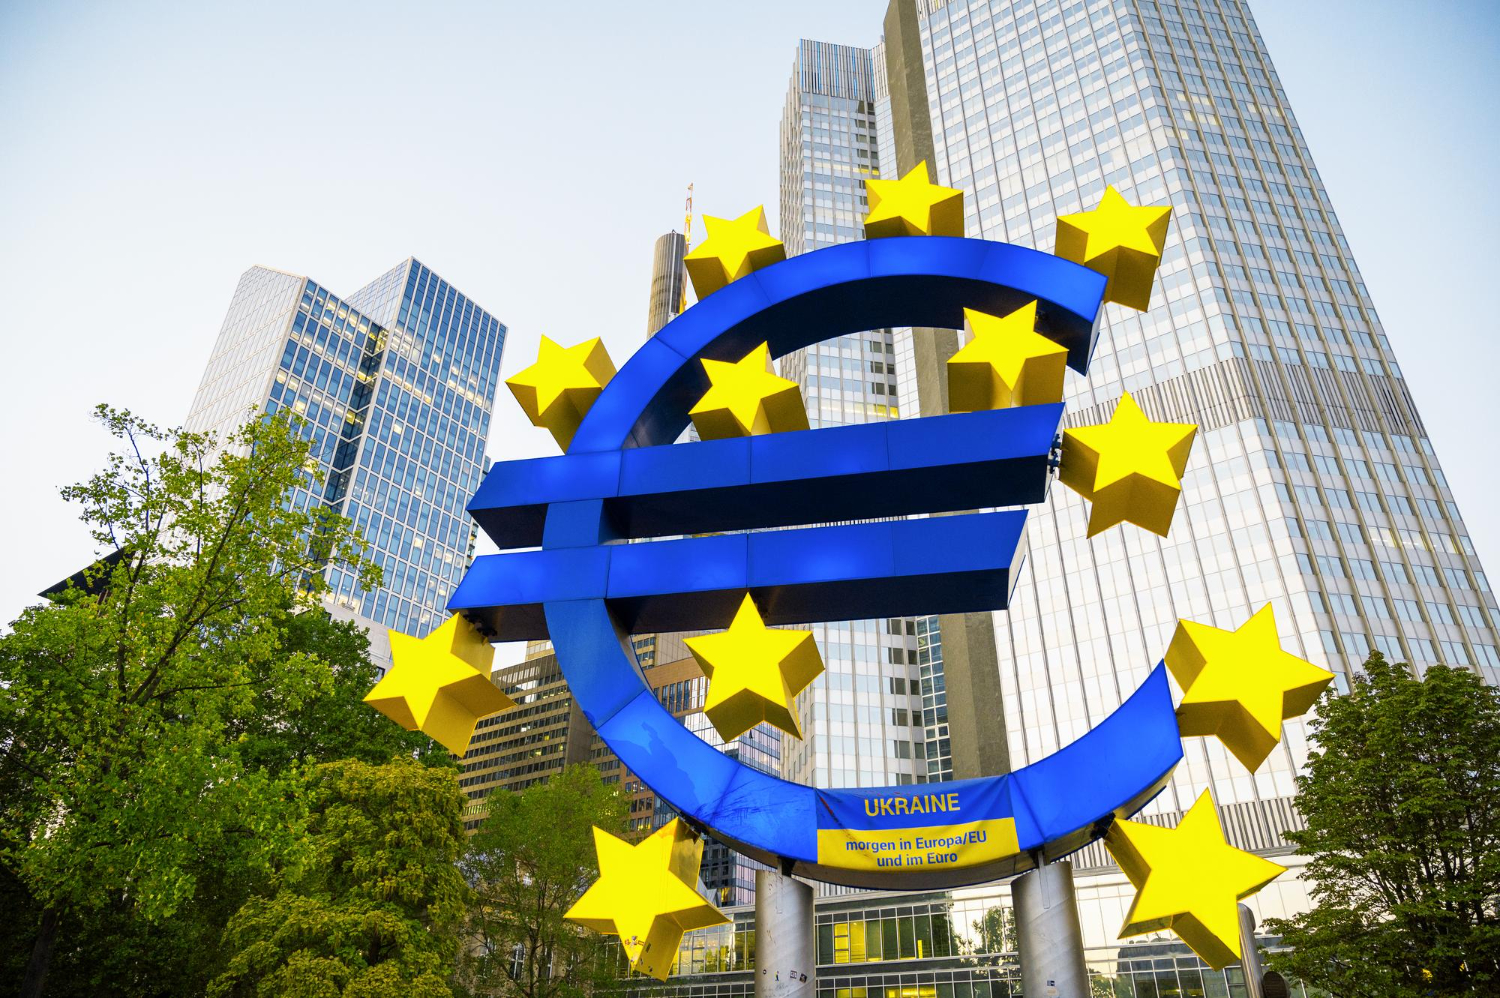
The EU's financial weaponization has backfired. Resulting in massive capital flight from European assets, euro depreciation, rising borrowing costs for EU governments, and the accelerated collapse of the euro's reserve currency credibility.
The European Union just made a catastrophic mistake.
[. . .]
Every country with reserves in European financial institutions had to reconsider their safety. If the EU would seize Russian assets, what stops them from seizing Chinese assets if tensions escalate over Taiwan? or Saudi assets if there's another oil dispute or any nation's assets in a future conflict. The answer, nothing stops them.
[. . .]
Central banks move slowly. But the direction became clear. Reduce European exposure. Increase holdings in jurisdictions with stronger property rights protections or less geopolitical ambition. Ironically, this included increasing holdings in Switzerland, neutral, Singapore, pragmatic, and even China, which now looked safer than Europe for non-western reserves. The European Union's aggressive use of financial warfare made European assets less attractive globally.
[. . .]
The sanctions and asset seizures were supposed to weaken Russia. Instead, they accelerated Russia's pivot away from Europe and integration with non western economies.
[. . .]
For 80 years, the postworld war II financial system operated on certain principles:
- Respect for sovereign property rights
- Sanctity of central bank reserves
- Political neutrality of financial infrastructure.
These principles were never perfectly upheld, but they were strong enough to maintain confidence in the system. The Russian asset seizure shattered these principles explicitly. Central bank reserves are no longer sacrosanked. They can be frozen and seized if the political climate supports it. Property rights are conditional. They depend on maintaining acceptable relations with Western powers. Financial infrastructure is weaponized. Swift custody systems and payment networks are tools of geopolitical competition. Once these principles are broken, they can't be easily restored.
[. . .]
This is how empires decline. Not through single catastrophic defeats, but through accumulated strategic mistakes that seem small at the time, but compound into disaster.
[. . .]
All of it resulted from choices made by European leaders who prioritized short-term political gains over long-term strategic thinking. Russia's response shocked Europe because European leaders didn't think it through. They assumed Western financial dominance was permanent, that sanctions and seizures could be imposed without consequence, that Russia had no effective retaliation options. They were wrong on all counts, and Europe will pay the price for this miscalculation for decades to come.
Here's the question nobody in Brussels wants to ask publicly. What happens when the costs of maintaining the Euro zone exceed the benefits for most of its members? Not in theory, not in abstract models, but in actual measurable economic outcomes that affect real people's lives. We're about to find out because that crossover point is approaching faster than almost anyone realizes. And when it arrives, the choices will be stark, brutal, and irreversible.
[. . .]
systematic calculated evacuation by sophisticated investors who've done the math and decided the riskreward calculation no longer favors keeping money in Europe. When I see this pattern, I don't see market volatility. I see a verdict. The smart money, the institutional money, the generational wealth that thinks in decades rather than quarters is quietly concluding that Europe's economic model is broken beyond repair. And they're not wrong. Let me explain why the Euro zone was always going to reach this point. Not because Europeans are incompetent or because the project was malicious, but because the fundamental architecture contains a contradiction that cannot be resolved within the current framework. When you create a monetary union without fiscal union, you're building a structure that's stable only under very specific conditions. Those conditions are similar productivity levels across member states, synchronized business cycles, high labor mobility, and willingness of stronger regions to permanently transfer resources to weaker ones. Europe has none of these, not even close. Productivity divergence between Germany and Greece is wider today than it was in 2001 when Greece joined the Euro. Business cycles across the Euro zone are more decynchronized now than they were before the common currency. Labor mobility remains constrained by language, culture, and regulatory barriers. And political willingness for fiscal transfers has collapsed entirely. This means the Euro zone is trying to operate a single monetary policy across economies that need radically different policies. When the European Central Bank sets interest rates, it's setting one rate for 19 different economic realities.
[. . .]
Northern Europeans believe they're subsidizing southern proflegacy. Southern Europeans believe they're trapped in a currency regime designed for northern benefit. Both views contain elements of truth which makes reconciliation nearly impossible. This is why I describe what's happening as controlled demolition rather than random crisis. The system is breaking along entirely predictable lines producing entirely predictable political reactions leading toward entirely predictable outcomes.
[. . .]
In 2024, net capital outflows from the Euro zone exceeded €400 billion. That's not total flows, which are always large. That's net outflows, meaning more money left than entered. It's the largest net outflow since the Euro zone's formation, exceeding even the 2012 crisis peak. Where is this money going? Approximately 30% to the United States, 25% to Switzerland, 15% to Britain, 10% to various Asian markets, and 20% to other destinations including gold and cryptocurrencies. What does this tell us? It tells us that global capital, including European capital, is systematically reducing exposure to Eurozone risk, not because of temporary uncertainty, but because of fundamental reassessment of the Eurozone's long-term viability.
[. . .]
the most alarming aspect isn't the total volume of outflows. It's the acceleration. Monthly outflows in the first quarter of 2025 average 42 billion EUR up from 23 billion in Q4 2024 up from 16 billion in Q3. The trajectory is exponential not linear. This pattern matches what we saw in the 18 months before the 2012 crisis erupted into public view. Capital doesn't flee all at once. It starts with the most sophisticated investors recognizing systemic problems early. Then institutional investors follow. Then smaller investors panic as they realize what's happening. By the time the general public understands the crisis, it's already well advanced. We're currently in the middle phase of that sequence.
[. . .]
Their [ECB] internal research papers acknowledge that one-sizefitsall monetary policy creates divergence rather than convergence. But they're trapped by their mandate and by the political impossibility of admitting the euro was a mistake. So they do what central banks always do when trapped. They buy time with unconventional policies while hoping something changes to make the fundamental problems go away. The balance sheet tells the story. The ECB's total assets reached € 8.9 trillion in early 2025, equivalent to 76% of Eurozone GDP. For comparison, the Federal Reserve's balance sheet is 37% of US GDP. The Bank of England's is 42%. The ECB is far more leveraged than other major central banks. What are those assets? mostly government bonds from member states purchased through various quantitative easing programs. In effect, the ECB has become the buyer of last resort for European sovereign debt, the only institution willing to absorb the massive bond issuance required to fund deficits that exceed official limits. This creates a dangerous dependency. Member states can only fund their deficits because the ECB buys their bonds. If the ECB stopped buying, yields would spike and several countries would face funding crisis immediately. But the more the ECB buys, the more dependent member states become and the larger the ECB's exposure to sovereign default risk. It's a debt trap[. . .]
which scenario I think is most likely and why. Orderly dissolution is the economically optimal outcome, but requires political courage that's currently absent. No major political party in any member state is willing to campaign on Euro exit despite growing evidence that exit would benefit their citizens. Chaotic collapse is increasingly likely as time passes without reform. The longer the current system persists, the more unstable it becomes and the higher the probability of some shocktriggering disorderly breakup. Temocratic authoritarianism is what European elites will try to implement if crisis creates the political opportunity.
[. . .]
Economists warned before the euro's launch that monetary union without fiscal union would create exactly these dynamics. The warnings were ignored because political will for integration overrode economic analysis. Now we're paying the price for that decision. And the price is measured not in abstract policy failures, but in lost growth, unnecessary unemployment, damaged careers, disrupted lives, and rising political extremism across the continent.
[. . .]
The political center that built and sustained the European project is collapsing because the economic model it created is failing to deliver prosperity.
[. . .]
The European establishment blames Russian disinformation or social media or populist demagoguery for the rise of extremism. But the real cause is economic. A generation of young people with no prospect of matching their parents' living standards, trapped in a monetary system that prioritizes creditor rights over economic recovery. As long as that system persists, political radicalization will accelerate. And the window for orderly reform is closing faster than most people realize.
[. . .]
I see time running out. The mathematics of debt, the psychology of capital flight, the politics of resentment, all are accelerating toward crisis. And when that crisis arrives, the options will be worse than the options available today. Europe can choose orderly reform now or chaotic collapse later. It can negotiate managed transition to more sustainable structures, or it can wait for markets to force brutal adjustment. It can act while still possessing some control over outcomes or it can wait until events control it. Current trajectory suggests waiting is more likely than acting and that waiting will prove catastrophically expensive.
[. . .]
Europe is not facing temporary policy challenges that better management could resolve. It's facing mathematical inevitability arising from structural contradictions built into the Euro zone's foundation. Those contradictions are now generating costs that exceed benefits for a growing number of member states. And when costs exceed benefits, systems break. That breaking point is approaching. Not in decades, in quarters or years. The capital flight data shows sophisticated investors already positioning for that outcome.
when they were forming the euro and so what happened was I explained this is how we create a currency etc. and you wanted to compete with the dollar, which was actually a most people don't realize, but that was the request of the United States out of 1985 out of the Plaza Acord that the dollar had gone up so high because there was no competition. So, that was Jim Baker basically saying that if Europe, you know, created a single currency, then that would compete against the dollar and prevent the dollar from going up to record highs all the time.
[. . .]
when I got called in in creating the euro, I explained that you have to consolidate the debt in order to compete with the dollar. And at the time Helmut Kolh was the chancellor and he admitted before he died if he allowed the German people to vote he would have lost seven to three. So he took Germany into the euro unilaterally and his condition was no consolidation of the debt. Because he felt that the Germans would view it as bailing out Greece or Italy, stuff like that. And I warned them. I said this is going to fail. Yeah, from a trader's perspective, I could pick up the phone and say, "Buy me$10 billion worth of US treasuries." No problem. Right. With Europe, I still have to make the same decision as if the euro didn't exist. Right. Do I want Italy? Do I want France? You know, you just look at all the peripherals, you know, the spreads between them. This is why there is no federal debt for Europe. So, you're still with the same country risk of each individual one. So nothing really changed. And that's why the euro has never been able to compete with the dollar, right. Because you still got as a fund manager, you still got to make the same decision as if the euro didn't exist.
The Collapse of Germany
German industrial production has fallen 11.2% year-over-year with nine consecutive months of decline—this isn't recession, this is deindustrialization. The cause: German electricity costs €0.25/kWh versus €0.08 in the US and €0.10 in China after Germany's catastrophic decision to shut down nuclear power while becoming dependent on Russian gas that no longer flows, making energy-intensive industries (chemicals, steel, automotive) economically unviable and forcing them to relocate or die. [. . .] Germany's middle class is being hollowed out exactly like America's Rust Belt and Britain's industrial collapse. Yet there's a conspiracy of silence: German media follows government line, European media won't discuss it because Germany's collapse threatens the entire EU project, politicians can't admit their green energy transition as implemented was economically catastrophic, [. . .] Germany represents 25% of eurozone GDP, finances European trade surpluses, funds EU institutions, and backs the euro's credibility—when Germany collapses, Europe collapses with it, and the economic engine that held the continent together for 30 years is breaking down while almost nobody talks about it.
they [The EU] created a federation,
21:22
a monetary federation a singular currency without a fiscal federation without a political federation. And that
21:28
is what you do if you want to create a permanent system of austerity
21:34
of very low investment of negative investment and of stagnation.
Related
As is now clear, the same policies that required the tragic and brutal suppression of Greece’s democratic uprising have led directly to authoritarianism, populist revolt and instability throughout the Western world.
[. . .]
There's no plan. [The EU] have no idea where they're going to find
43:44
find the money. you know, even the 800 billion of for von der Leyen for the rearm
43:50
program is borrowed money that nobody's going to borrow because they don't have the fiscal buffers to accommodate it.
43:56
How are they going to help Ukraine? They borrowed 90 billion. That's their limit. They can't borrow
44:02
more. They are already, you know, the the European community budget is now
44:07
under a lot of strain. And you know France wants to reduce its contributions to the European budget not
44:14
increase it. So they don't have a plan for war. Ask them, okay what's your plan for peace? They don't have a plan for
44:20
peace. They don't have a plan for the energy union. They don't have a plan and
44:27
they are going from announcement to announcement that resemble smoke and mirrors. Each announcement is less
44:35
credible than the previous one. Now they're going to bring Canada into the European Union, which is preposterous because you know, I mean,
44:42
[laughter] but are they going to bring Canada into the single market and charge the
44:47
Canadians for participating the creation of rules and regulations that the Canadians will have no authority over?
44:55
This is absurd. Every single thing that comes out of the lips of Kaja Kalas or of von der Leyen
45:03
just reminds us of the fact that the European Union is a figment of our collective imagination.
[. . .]
Let me make a prediction as to when he Germany is going to die.
49:47
It will die when the when Beijing decides to turn BRICS Plus into a
49:52
Breton Wood system. Remember how I was describing the Breton Wood system as a system of fixed exchange rates or
50:00
quai fixed exchange rates where the hedgemon the surplus power which would
50:05
now be China recycles it surpluses to the other countries within this new Breton Wood
50:12
within this BRICS Plus system and maintains the fixed exchange rates
50:18
using it the power of its own surpluses. When China decides to do that, to play
50:24
the role within the BRICS Plus countries, then the United States stateates played within the Breton Wood
50:30
system after 1944, then the United States is going to be in
50:35
serious trouble and they know it. This is one of the fundamental reasons why they're upping the tensions with
50:41
the Chinese.
[. . .]
they're not prepared to you know to stir the pot
51:50
yet. They want to make sure that the infrastructure is in place before they go for you know in that
51:56
direction and they, my understanding or at least my speculation if you want, is
52:02
that they want to let the Americans cross at the Rubicon. The Americans have
52:07
not crossed the Rubicon yet.
Articles: